
Ipswich Commercial Property Sales (Q2 2025) at a Glance
- Big tickets: Warrego Industrial Park at $35.5m and the Orion Hotel at $30m top the sold list. Town Square Redbank Plains on market around $150m mark.
- Everyday staples: Drive-thrus and essentials are hot — Starbucks Ripley sold for $5.54m and 7-Eleven/Subway for $8.15m — while childcare and medical keep trading in the mid range.
- What to watch: Redbank Motorway Estate, CitiSwich, BrisWest, Springfield’s growing health hub, and Ripley’s boom corridor.
Welcome to the hub for Ipswich commercial property sales.
What you get (free):
- A rolling two-year TOP 20, updated quarterly, ranking single-asset deals inside the Ipswich City Council LGA by price.
- Prices are published figures, or clearly labelled estimates where a published yield or rent allows clean maths.
- On-market heavyweights appear for context. Dates are announcement unless noted. Every entry links to a source.
More Ipswich Gold
$30m+
~$150m guide — Town Square Redbank Plains — Redbank Plains
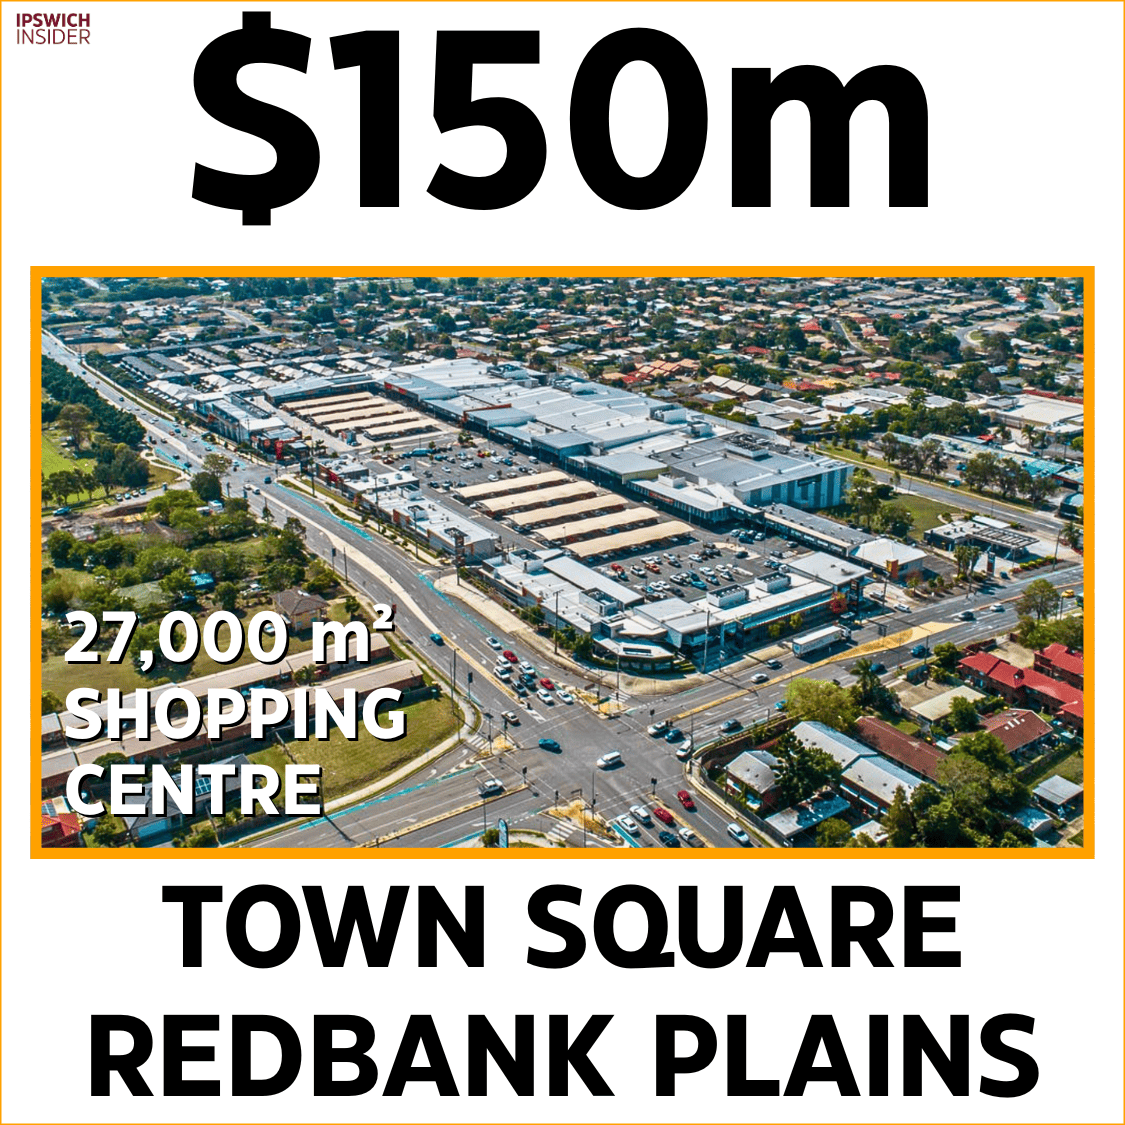
Category: Retail • Asset: Freehold sub‑regional centre offered as one going concern across multiple titles, ~27,326 m² GLA i; anchors Coles, Woolworths, ALDI, Target
Details
- Status: On market EOI i guide around $150m unsold
- Date (EOI closed): 27 Mar 2025
- Parties involved: Vendor Sim Lian Metro and marketing by JLL with Stonebridge
- Agent: JLL Retail Investments and Stonebridge Queensland
- Full story/source: Stonebridge 2025 listing • 2017 sale ~$160m (Inside Retail) • 2019 coverage (CRE)
$35.5m — Warrego Industrial Park 67ha — North Tivoli
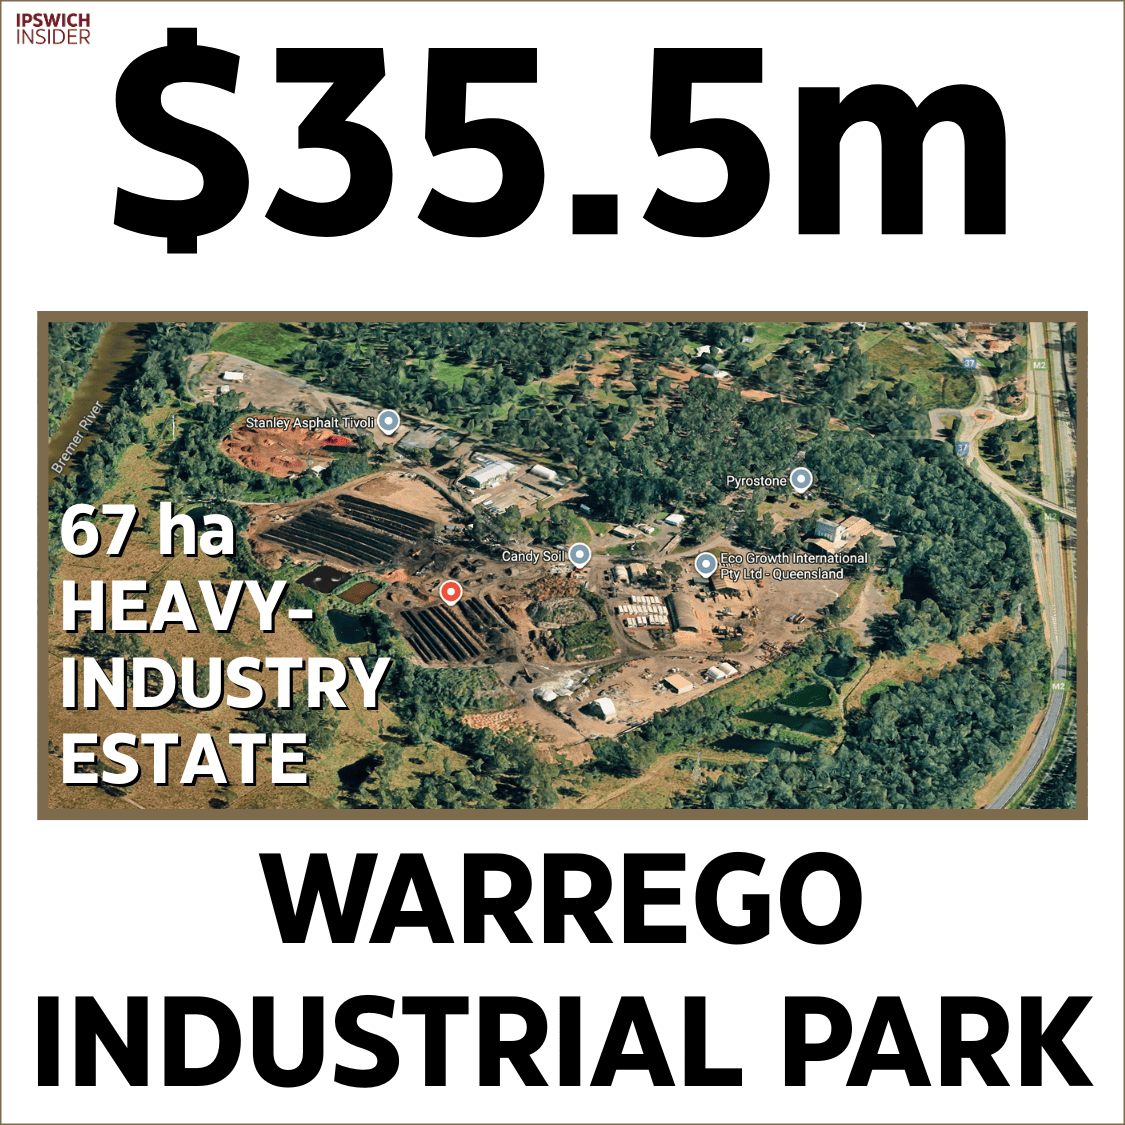
Category: Industrial • Asset: Freehold 67 ha heavy‑industry estate with broad‑acre hardstand & improvements; multi‑occupier; land‑rich with value‑add potential
Details
- Status: Sold off market
- Date (announcement): 19 May 2024
- Parties involved: Buyer Centennial and Seller undisclosed
- Agent: Blue Commercial
- Full story/source: Blue Commercial release
$30.0m — Orion Hotel — Springfield Central
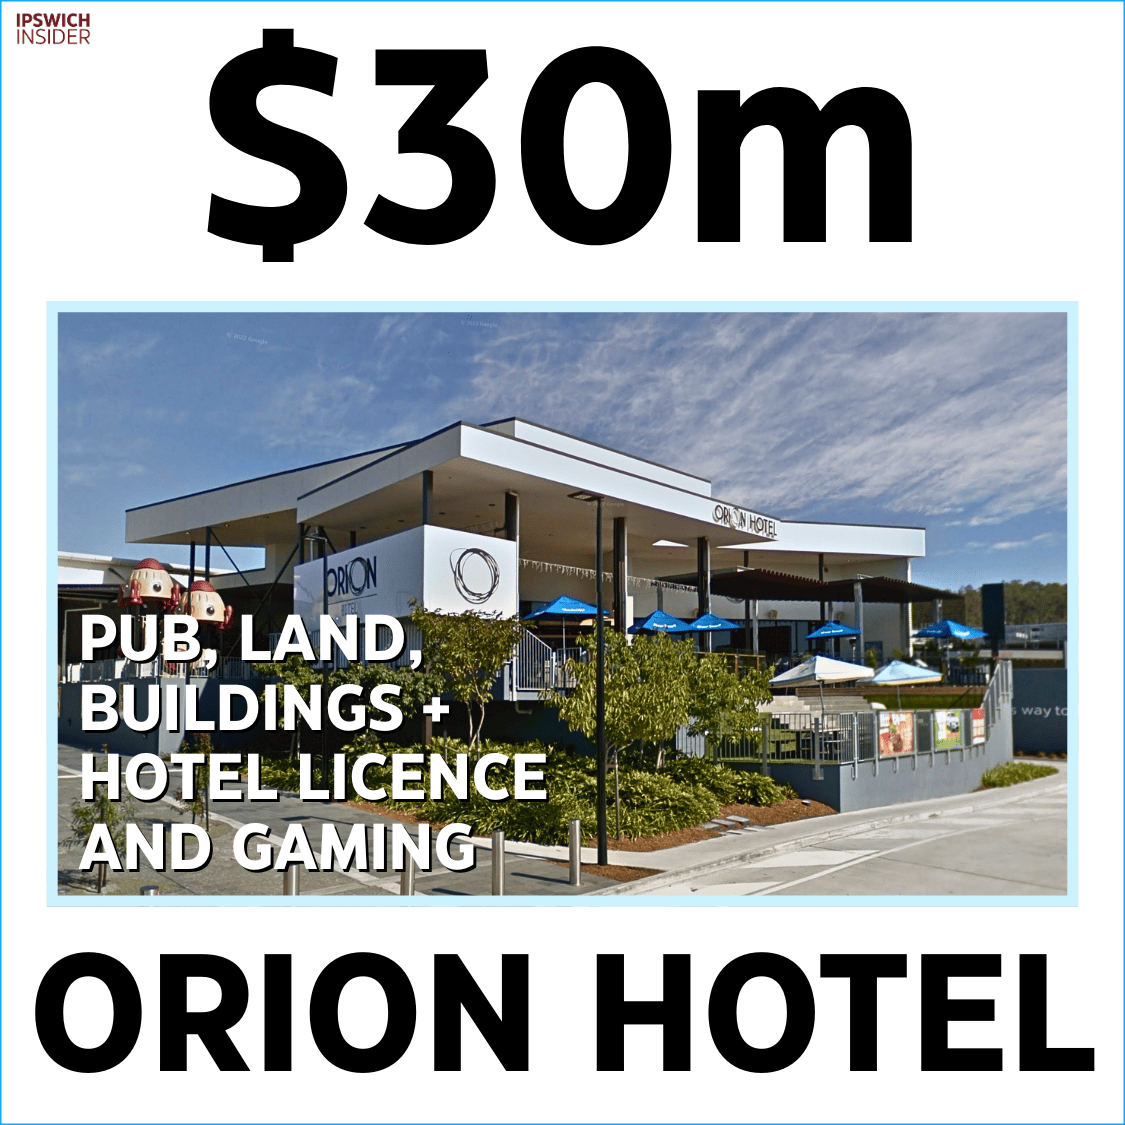
Category: Hospitality • Asset: FGC i pub within Orion; land & buildings + hotel licence + gaming entitlements
Details
- Status: Sold
- Date (announcement): 7 Aug 2025
- Parties involved: Buyer Redcape Hotel Group and Seller Jim Davies
- Agent: CBRE Hotels and JLL Hotels
- Full story/source: The Hotel Conversation
$10m to $30m
$26.7m — Quest Springfield Central 82 keys — Springfield Central

Category: Hospitality • Asset: Freehold 82‑key serviced‑apartment hotel + ground‑floor retail; sold subject to long hotel lease
Details
- Status: Sold with 7.65 percent yield reported
- Date (announcement): 29 Sep 2025
- Parties involved: Buyer Serene Capital and Seller 90 North
- Agent: Savills
- Full story/source: The Hotel Conversation
$23.0m — Redbank Plains Retail Centre — Redbank Plains
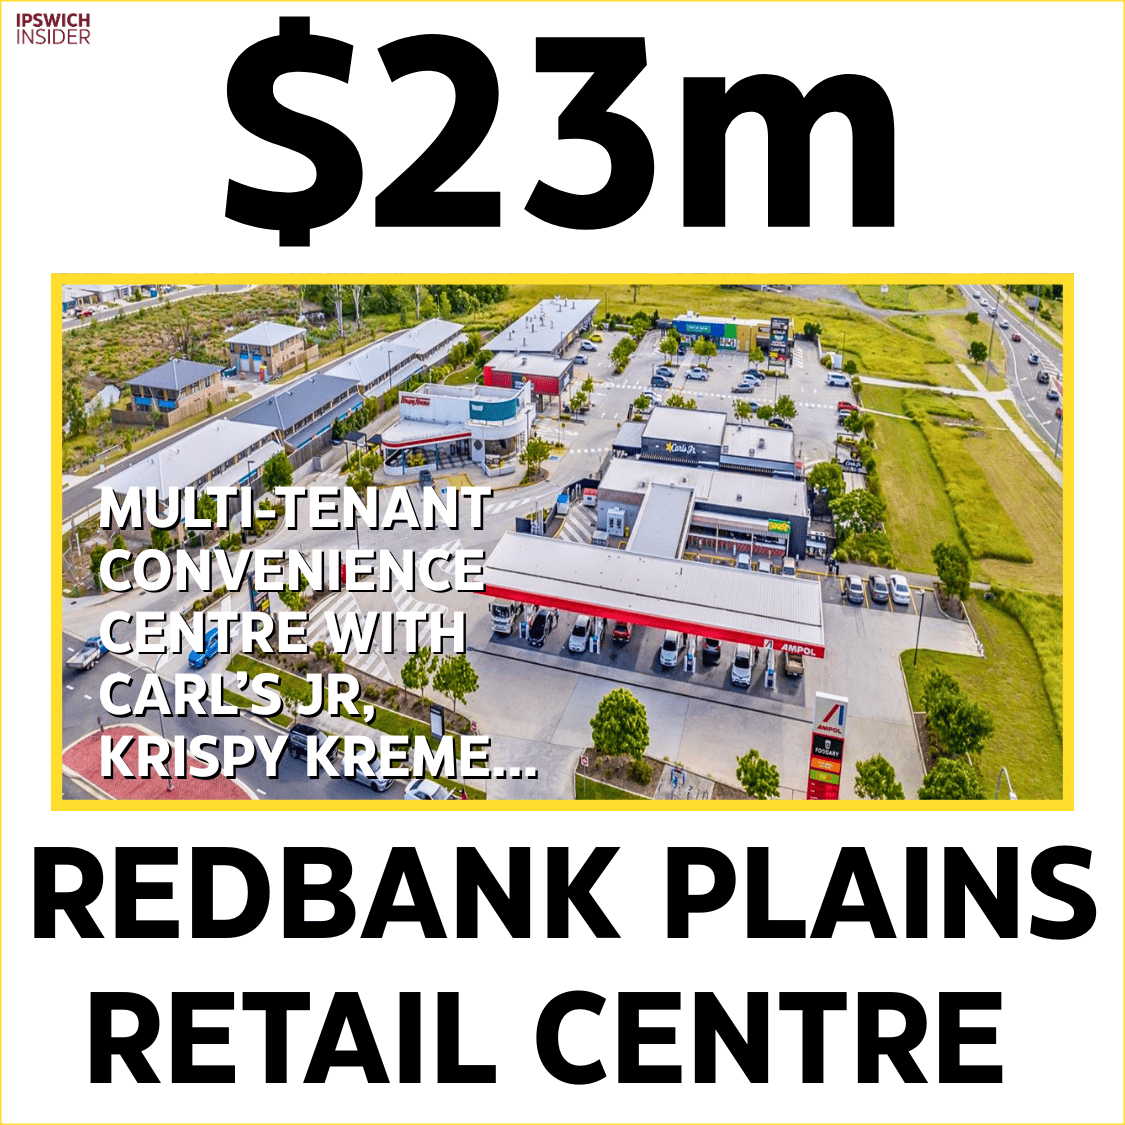
Category: Retail • Asset: Freehold multi‑tenant convenience centre with Ampol fuel and QSR i pads incl. Carl’s Jr, Krispy Kreme, Zarraffa’s
Details
- Status: Sold
- Date (settlement reported): 12 Mar 2024
- Parties involved: Buyer Westbridge Diversified Fund No 4 and Seller Charter Hall Long WALE i REIT i
- Agent: CBRE
- Full story/source: Green Street News • Sold listing
$21.0m ask — Country Motel Ipswich FGC i — Raceview
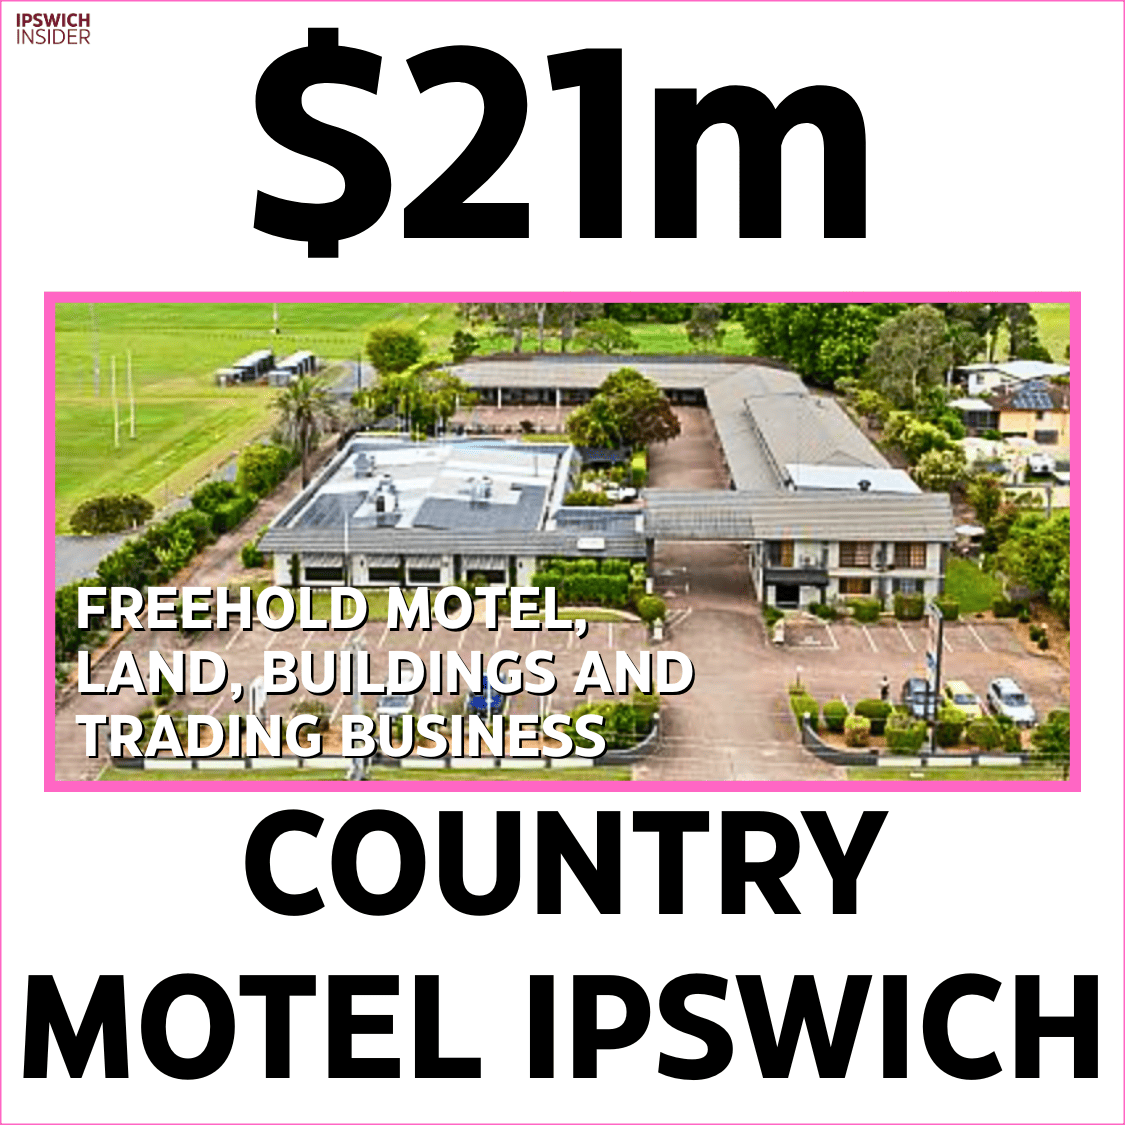
Category: Hospitality • Asset: Freehold motel including land, buildings & trading business; not a leaseback‑only
Details
- Status: On market freehold going concern asking $21m
- Date (listing): 2025
- Parties involved: Seller Country Motel Ipswich and Buyer to be confirmed
- Agent: ResortBrokers
- Full story/source: ResortBrokers listing
$20.5m — 45 Hume Drive multi tenant industrial ~9,919 sqm — Bundamba
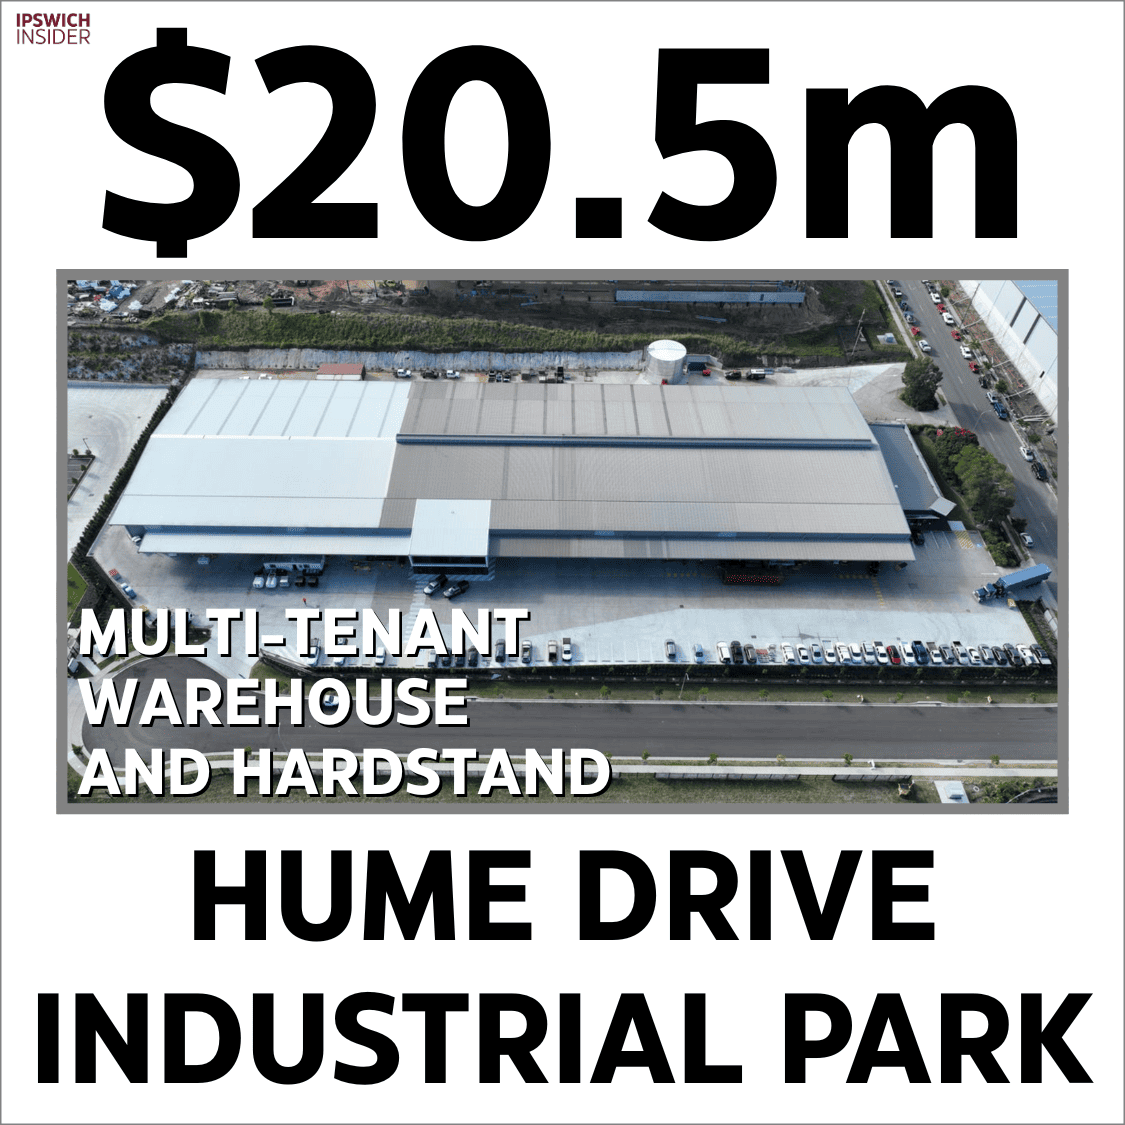
Category: Industrial • Asset: Freehold multi‑tenant warehouses totalling ~9,919 m² on 2.2 ha with hardstand; income‑producing with development upside
Details
- Status: Sold
- Date (announcement): 8 Jul 2025
- Parties involved: Buyer AsheMorgan and Seller Centuria
- Agent: Colliers
- Full story/source: RealEstateSource
~$19.6m est. — Commercial Hotel — Redbank
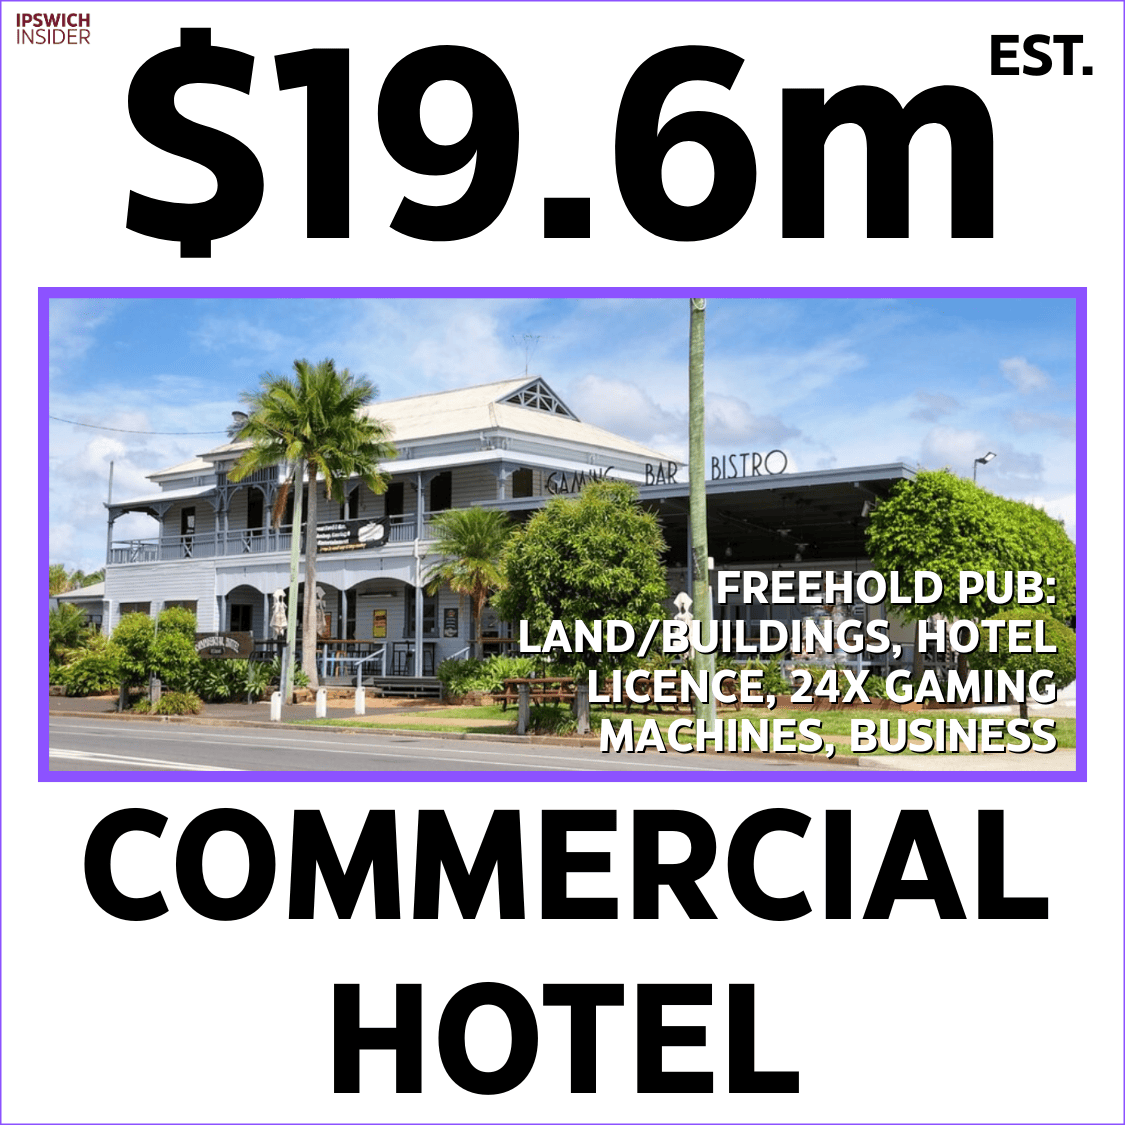
Category: Hospitality • Asset: FGC i pub — land & buildings, hotel licence, ~24 EGM i authorities; operating business included
Details
- Status: Sold with price undisclosed estimated from portfolio and EGM i metrics
- Date (portfolio announcement): 18 Dec 2024
- Parties involved: Buyer Redcape and Sellers private vendors
- Agent: HTL Property
- Full story/source: The Shout
~$18.6m est. — 38 Birdwood Crescent industrial land 33,906 sqm — Redbank
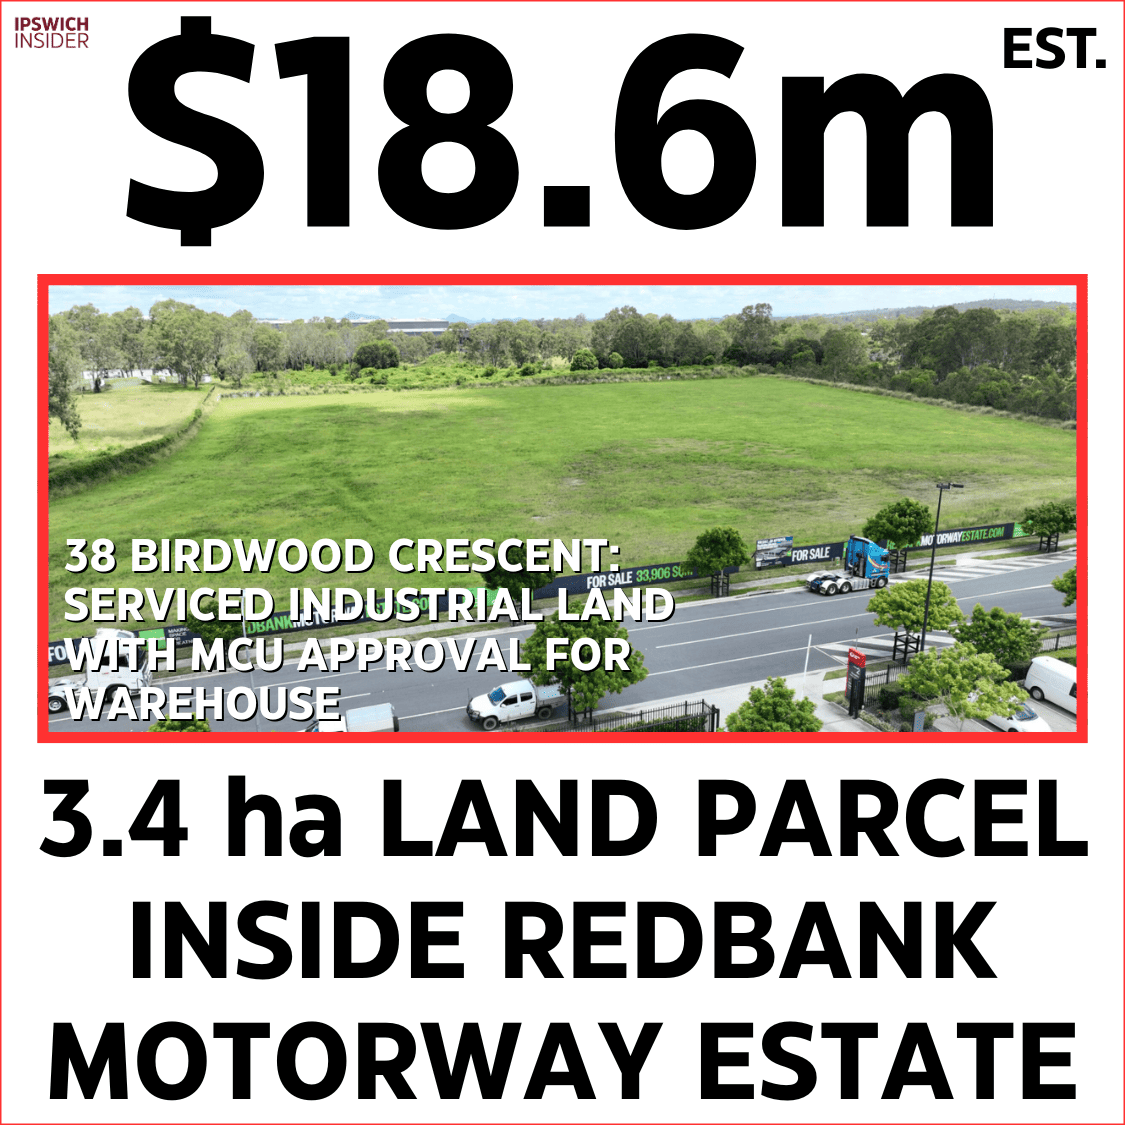
Category: Industrial • Asset: Freehold serviced industrial land 33,906 m² with MCU i for warehouse; purchaser to develop ~9,000 m² facility; no passing income at sale
Details
- Status: Sold with price undisclosed estimate based on SEQ industrial land benchmarks
- Date (announcement): 9 Oct 2025
- Parties involved: Buyer Kent Relocation Group and Seller Goodman
- Agent: CBRE
- Full story/source: CBRE press release
~$15.3m est. — Quest Ipswich hotel — Ipswich
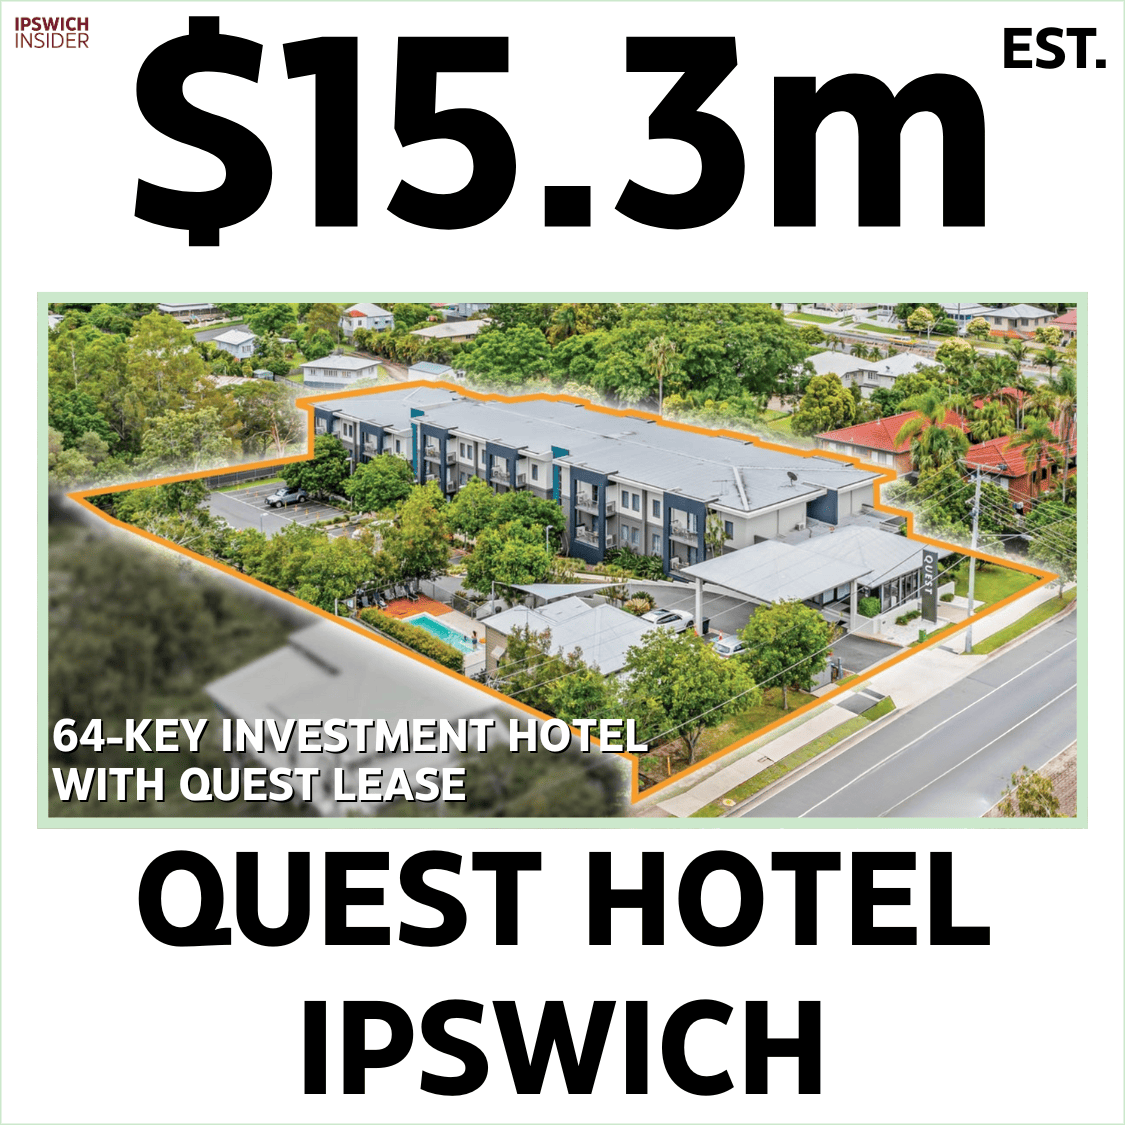
Category: Hospitality • Asset: Freehold investment hotel (≈64 keys) with on‑site parking; sold subject to lease to Quest; not a strata sell‑down
Details
- Status: Sold with price undisclosed estimate from published NOI i and comp yield
- Date (sold record): 26 Aug 2025
- Parties involved: Buyer undisclosed and Seller undisclosed
- Agent: Burgess Rawson and HTL Property
- Full story/source: RealCommercial sold record
$15.0m — The Hub medical plus childcare ~2,300 sqm — Goodna
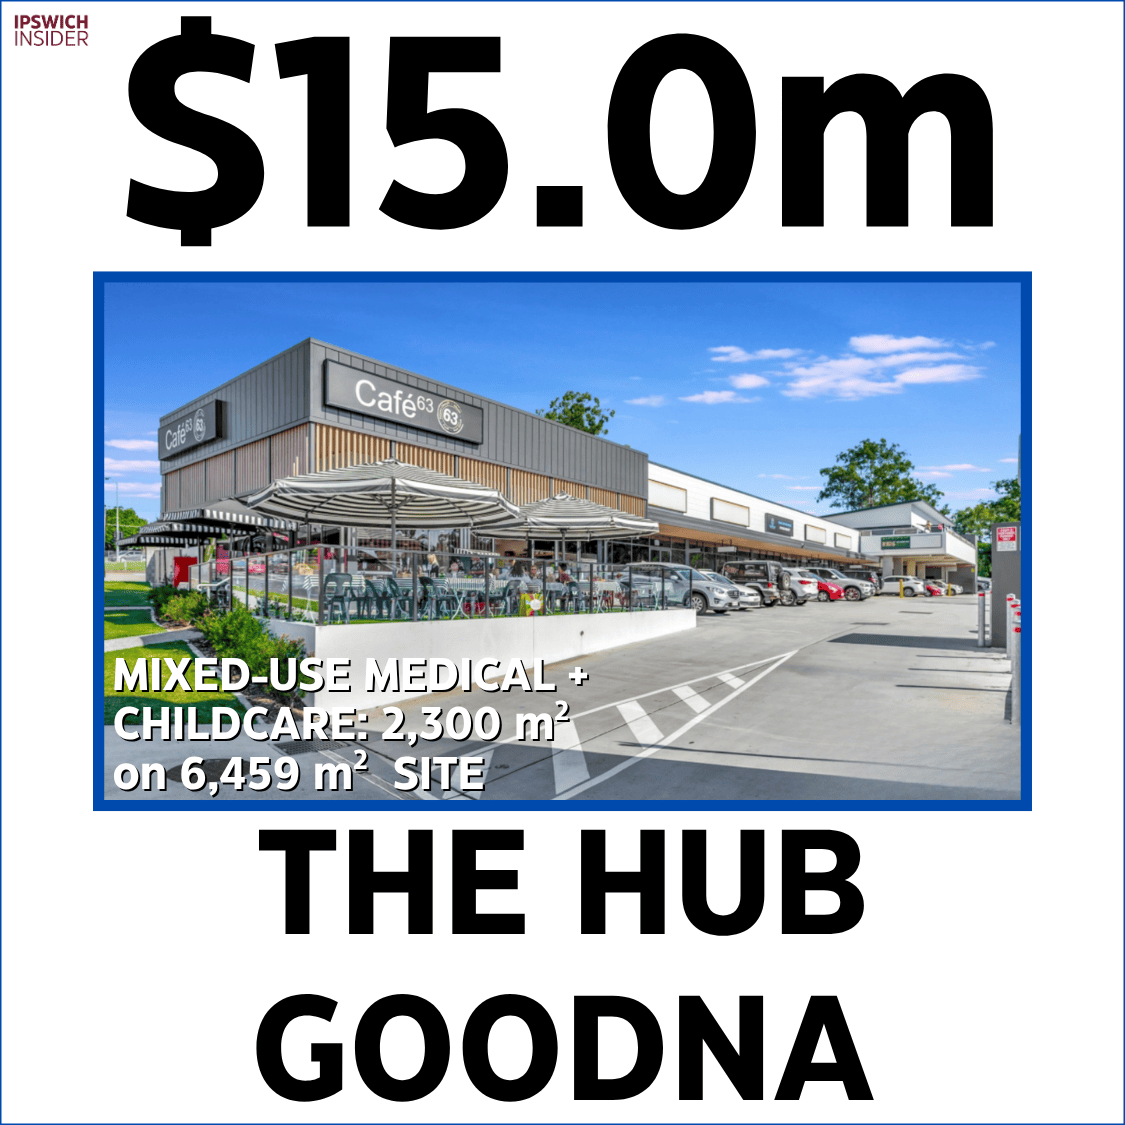
Category: Community • Asset: Freehold mixed‑use medical + childcare centre ~2,300 m² on 6,459 m² site; long leases to medical tenants & a childcare operator
Details
- Status: Sold on an essential services asset with reported 6.56 percent yield
- Date (announcement): 6 Jun 2024
- Parties involved: Buyer Victorian private investor and Seller private developer
- Agent: Colliers
- Full story/source: PropertyMarkets.News
$11.45m — Baby Bunting and RSEA LFR i ~2,723 sqm — Booval

Category: Retail • Asset: Freehold two‑tenant LFR i (~2,723 m² GLA i); national brands; long leases; on‑grade parking
Details
- Status: Sold
- Date (announcement): 6 Oct 2025
- Parties involved: Buyer private investor and Seller Properties and Pathways
- Agent: JLL
- Full story/source: PropertyMarkets.News
$10.25m — Raceview Shopping Centre plus 16 units — Raceview

Category: Retail • Asset: Freehold neighbourhood centre + 16 residential units across 4 titles on 1.38 ha; income today with value‑add/redevelopment angles
Details
- Status: Sold
- Date (sold record): 31 Oct 2024
- Parties involved: Buyer Unison Projects and Seller Glode family
- Agent: Blue Commercial
- Full story/source: Blue Commercial release
$5m to $10m
$8.15m — 7 Eleven and Subway dual tenant — Ripley

Category: Retail • Asset: Freehold fuel + QSR i drive‑thru corner site; modern build; net leases to national brands
Details
- Status: Sold with 5.63 percent yield
- Date (announcement): 8 Jul 2025
- Parties involved: Buyer private investor and Seller Griffith Group
- Agent: Stonebridge Property Group
- Full story/source: PropertyMarkets.News
$7.60m — Little Locals Childcare 154 places — Ripley
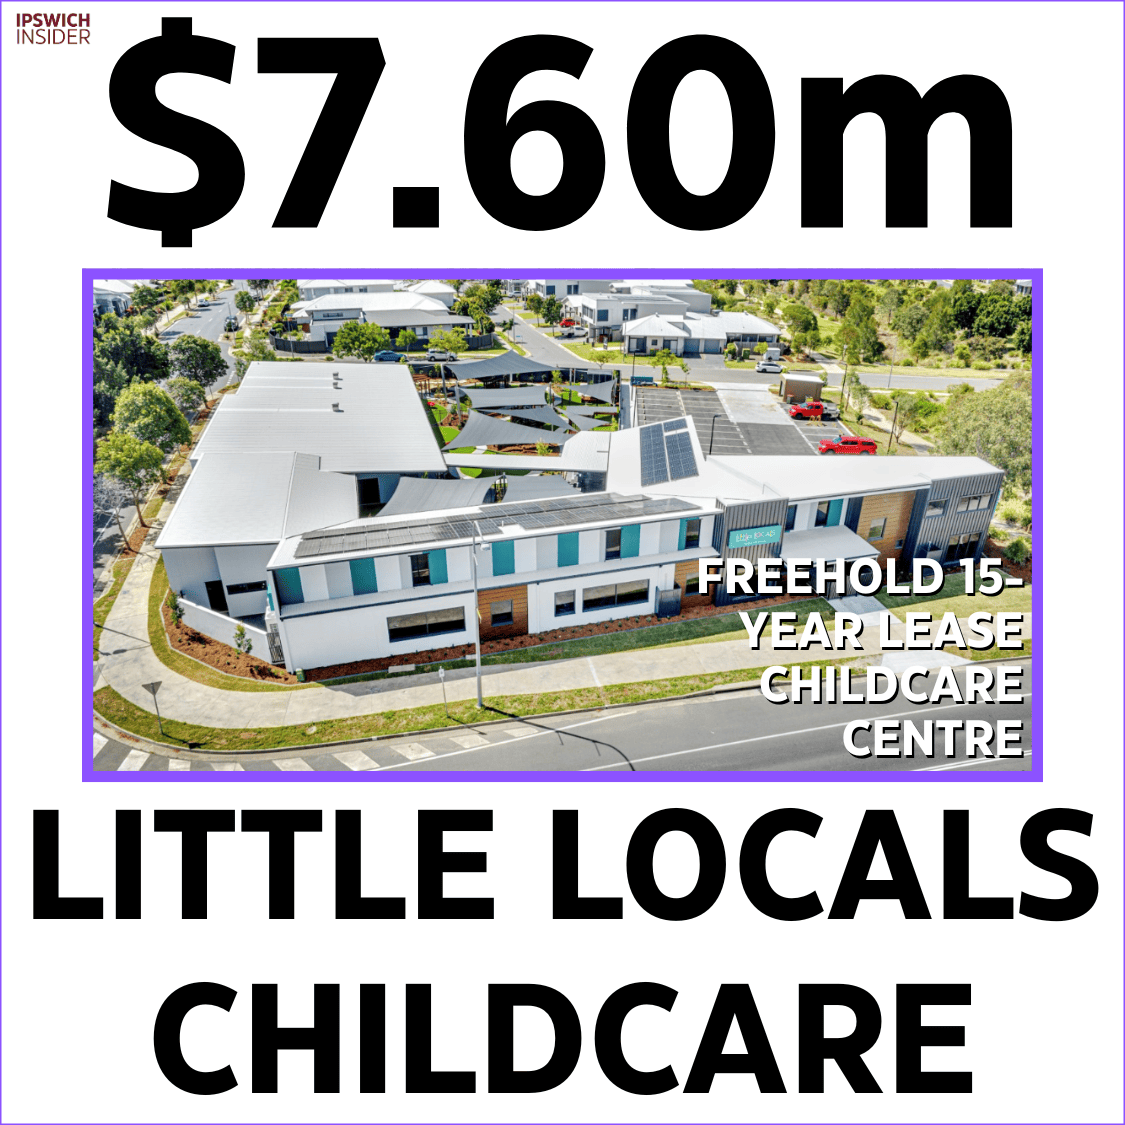
Category: Community • Asset: Freehold 154‑place childcare; 15‑year net lease to operator; purpose‑built improvements
Details
- Status: Sold with ~5.4 percent yield
- Date (announcement): 29 Apr 2024
- Parties involved: Buyer Brisbane private investor and Seller Clarence Property
- Agent: CBRE
- Full story/source: CBRE press release
$7.10m — Karalee Medical Centre — Chuwar
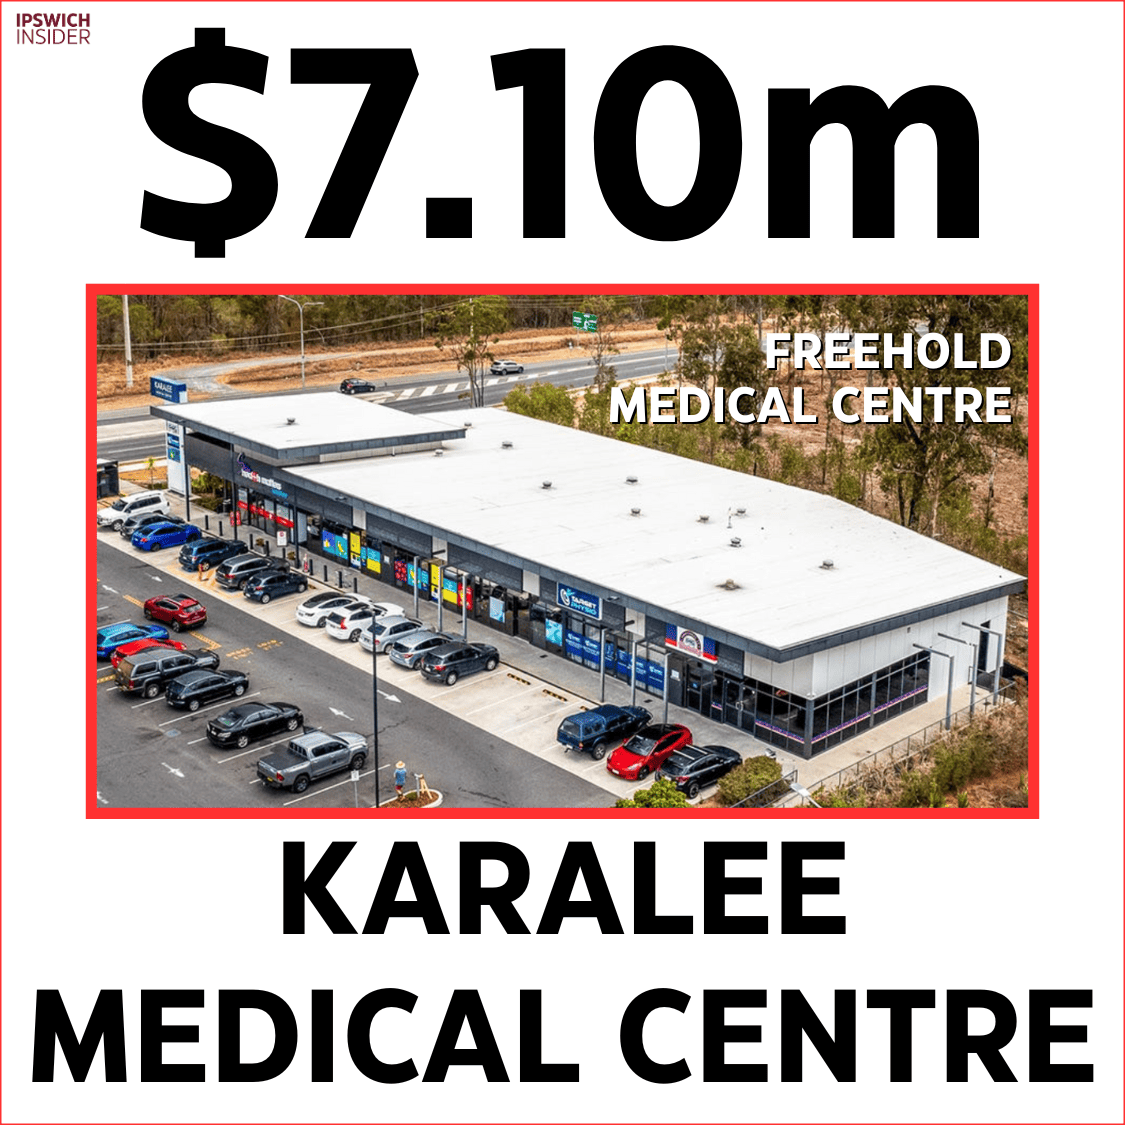
Category: Community • Asset: Freehold multi‑tenant medical centre adjacent to Karalee Village; longer leases; net income profile
Details
- Status: Sold with 6.5 percent yield
- Date (announcement): 22 Apr 2024
- Parties involved: Buyer private investor and Seller private owner
- Agent: Burgess Rawson
- Full story/source: COMMO deal note
$6.17m — Ripley Central strip retail multi tenant — Ripley
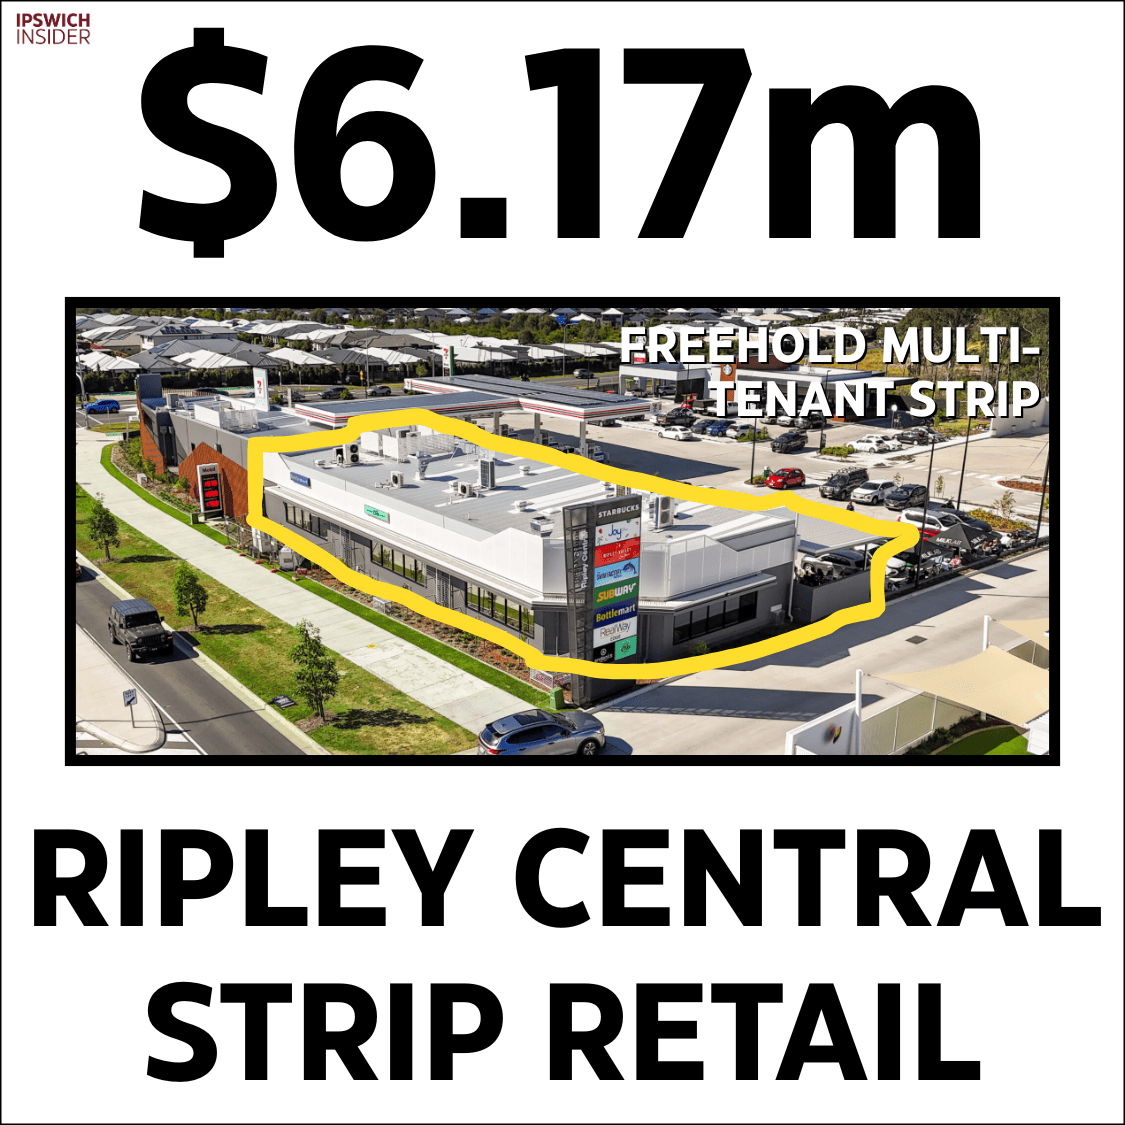
Category: Retail • Asset: Freehold multi‑tenant strip with convenience retailers (Bottlemart, The Cheesecake Shop etc.); on‑grade parking
Details
- Status: Sold with 5.49 percent yield
- Date (announcement): 3 Oct 2025
- Parties involved: Buyer private investor and Seller Griffith Group
- Agent: Stonebridge Property Group
- Full story/source: PropertyMarkets.News recap
$5.54m — Starbucks drive thru Ripley Central — Ripley
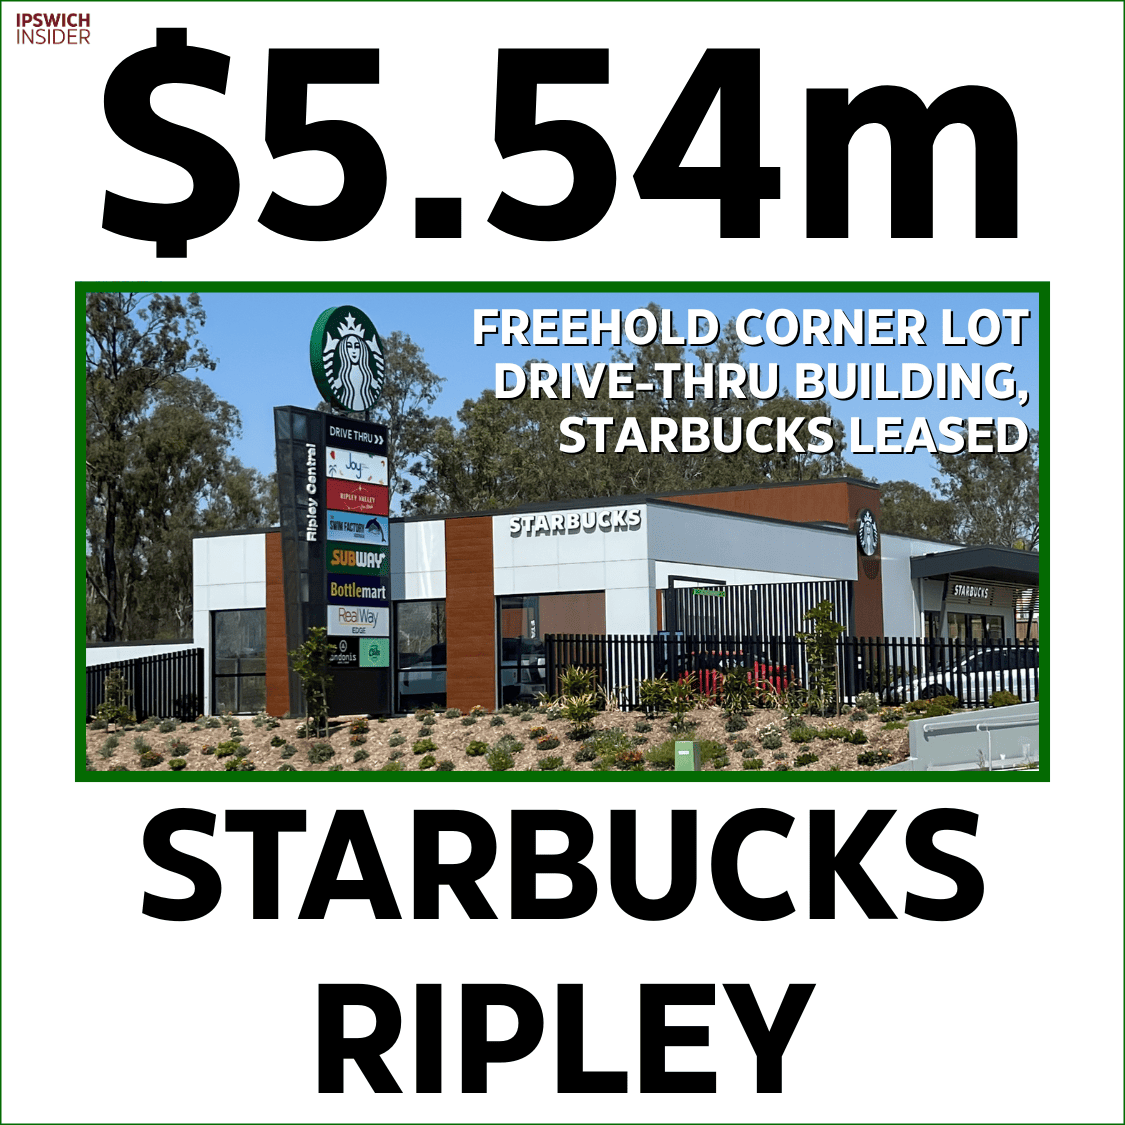
Category: Retail • Asset: Freehold single‑tenant drive‑thru building; 12‑year net lease to Starbucks; new construction
Details
- Status: Sold with 4.59 percent auction yield
- Date (auction sold): 14 Aug 2025
- Parties involved: Buyer private investor and Seller Griffith Group
- Agent: Stonebridge Property Group
- Full story/source: PropertyMarkets.News recap
Less than $5m
$3.27m — 43–45 Belar Street industrial — Yamanto
Category: Industrial • Asset: Freehold light‑industrial property with multiple warehouse/tenancy bays; leased to local trade businesses
Details
- Status: Sold multi tenanted small bay industrial
- Date (sold record): 24 Sep 2025
- Parties involved: Buyer private investor and Seller private owner
- Agent: K2 Private Property
- Full story/source: CommercialRealEstate sold page
~$2.99m est. — Sparkletown Car Wash Ripley Central — Ripley
Category: Retail • Asset: Freehold single‑tenant automatic car wash; 10‑year net lease; specialist plant tenant‑operated
Details
- Status: Sold with price undisclosed estimate via NOI i and portfolio remainder
- Date (sold record): 29 Aug 2025
- Parties involved: Buyer private investor and Seller Griffith Group
- Agent: Stonebridge Property Group
- Full story/source: Stonebridge listing with NOI
Noteworthy
Future Potential
- ~$350–$405m — Orion Springfield Central — larger than Riverlink by GLA i and MAT i
- ~$295–$340m — Riverlink — big CBD centre but likely below Orion on value
- ~$150m guide — Town Square Redbank Plains — current on-market heavyweight
- $250–$330m — Officeworks 77,100 m² DC i (Redbank) — hypothetical single-asset sale once stabilised
- $1B+ — Redbank Motorway Estate Goodman-owned portfolio — would be a multi-asset package not single-asset
Illustrative ballparks only, based on GLA, rent bands and recent yields. For single-asset rankings we exclude portfolios.
All-time Biggest Ipswich Sales (Single Assets)
- $145.2m — Icon Ipswich, 117 Brisbane St (office), Ipswich CBD — 2021 RealEstateSource →
- $70.718m — “Elevation at Citiswich” 21.47 ha industrial land, Bundamba — 2023 RealEstateSource →
- $38.5m — 103 Riverview Rd “Riverview Industrial Park” site, Riverview — 2023 TheIndustrialist →
- $35.5m — Warrego Industrial Park 67 ha, North Tivoli — 2024
- $30.45m — St Ives Shopping Centre (+ six adjoining titles in one line), Goodna — 2019 CommercialRealEstate →
Note: single-asset for leaderboard purposes. St Ives traded “in one line” across multiple titles.
How We Estimated the “est.” Prices
- Commercial Hotel, Redbank (~$19.6m est.) —
Two-step: (1) apportioned Redcape’s QLD portfolio using venue gaming weight (24 EGM) and scale; (2) cross‑checked at a gaming‑pub yield band ~6.8–7.2% on an indicative NOI.
Price ≈ NOI ÷ yield → midpoint ≈ $19.6m. - 38 Birdwood Cres (~$18.6m est.) —
33,906 m² × serviced land rate (Western Corridor 2025) ≈ $540–$560/m².
Price ≈ area × rate → ~$18.3–$19.0m; midpoint ≈ $18.6m. - Quest Ipswich (~$15.3m est.) —
Published NOI ≈ $1.1715m p.a.; cap‑rate band 7.5–7.9% (anchored to Quest Springfield at 7.65%).
Price ≈ NOI ÷ yield → ~$14.8–$15.6m; midpoint ≈ $15.3m. - Sparkletown Car Wash (~$2.99m est.) —
NOI $180,500 p.a.; new build, 10‑year net lease yield band 6.0–6.5%.
Price ≈ NOI ÷ yield → ~$2.78–$3.01m; midpoint ≈ $2.99m.
Notes: “est.” figures use midpoints of reasonable market bands; all AUD, net yields (pre costs). We flag these as estimates because vendors/buyers did not publish a price.
How We Do Commercial Property Categories
- Industrial: Buildings and yards used to make, store, or move goods (warehouses, factories, logistics hubs, workshops, hardstand).
- Retail: Premises selling goods and services to the public (shops, shopping centres, large-format retail). Includes fuel stations and car washes.
- Hospitality: Food, drink, entertainment and short-stay accommodation (pubs, clubs, bars, restaurants, cafes, function centres, hotels/motels).
- Office: Workplaces for professional and administrative services (from suites to towers). Medical/clinical tenancies sit under Community.
- Community: Essential services: healthcare/medical, childcare, education, aged care, government and emergency services, plus libraries and civic facilities.
Classification rule: Mixed-use assets are assigned to the dominant income category.
Glossary
Area & Size
- GLA: Gross Lettable Area. Rentable area used for shopping centres.
- NLA: Net Lettable Area. Rentable area for office or industrial excluding shared areas.
- GFA: Gross Floor Area. Total under-roof building area including non-rentable space.
Income & Valuation
- MAT: Moving Annual Turnover. Last 12 months of retail sales.
- NOI: Net Operating Income. Income after property operating costs, before debt and tax.
- Yield: NOI divided by price. Also called the capitalisation rate.
- Cap rate: Another term for net yield. Value ≈ NOI ÷ cap rate.
- Passing rent: Current contracted rent being paid today.
- Net lease: Tenant pays most outgoings. Landlord covers little.
- Gross lease: Landlord pays most outgoings. Rent is a gross figure.
Tenancy & Deal Structure
- WALE: Weighted Average Lease Expiry. Lease term left, weighted by income.
- EOI: Expressions of Interest sale method with a closing date for offers.
- FGC: Freehold Going Concern. Sale includes the real estate and the operating business.
- LFR: Large Format Retail. Bulky-goods retail such as homemaker centres.
- QSR: Quick Service Restaurant. Drive-thru or counter-service food outlet.
- DC: Distribution Centre. Large warehouse for logistics and fulfilment.
- ADC: Automated Distribution Centre. DC with significant automation.
- EGM: Electronic Gaming Machine in pubs or clubs.
- Guide price: Indicative price talk from agents or media.
- On market / Off market: Publicly advertised vs privately transacted.
Planning, Location & Dates
- DA: Development Application to council for approval.
- MCU: Material Change of Use. DA to change or approve land use.
- LGA: Local Government Area. Council boundary used for eligibility.
- CPI: Consumer Price Index. Used to restate past prices in today’s dollars.
- Announcement date: When the sale was publicly announced.
- Auction sold date: The date the hammer fell at auction.
- Settlement date: When ownership and funds formally transfer.